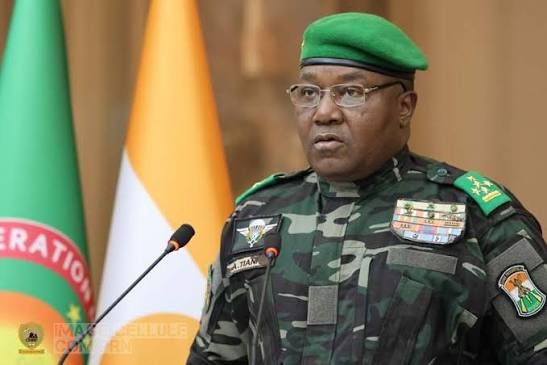
The Nigerien government’s bold vision of economic sovereignty and a definitive break from external influence has collided with the harsh realities of its fiscal challenges. On October 8, 2026, the International Monetary Fund (IMF) announced the conclusion of a staff-level agreement following a mission to Niamey, signaling a decisive shift in the country’s economic trajectory.
From rhetoric to reality: the IMF’s 38-month financial oversight
The new Extended Credit Facility (ECF) program, spanning 38 months, represents the tenth and final review under the current arrangement. Approved by the IMF’s Executive Board in December 2026, it unlocks a substantial package totaling 150.02 million SDRs (approximately $203 million), equivalent to 114% of Niger’s quota.
The agreement includes an immediate disbursement of 26.3244 million SDRs (about $36 million) to stabilize public finances and address pressing external financing needs. This infusion of funds arrives just as the government faces mounting pressure to fund its ambitious Programme pour la refondation de la République (2025–2029).
Oil boom vs. fiscal deficit: the economic tightrope
Despite projected oil-driven GDP growth of 7% in 2026, 6.7% in 2027, and an average of 6.1% over the medium term, the budget remains mired in deficit. The government’s optimistic forecasts mask deep structural issues, including an inflation rate projected to swing from -2.5% in 2026 to 2.2% in 2027—a fluctuation driven largely by soaring transportation costs amid regional instability.
These economic hurdles are compounded by the need for post-disaster reconstruction, emergency subsidies, and overwhelming security expenditures. The result? A projected budget deficit of 3.4% of GDP for 2026, leaving the government with no choice but to seek external financing to sustain its refoundation agenda.
Sovereignty vs. conditionality: the paradox of financial independence
The IMF’s terms for the new program are clear: deeper structural reforms, including enhanced fiscal capacity, stricter public debt management, and sweeping financial sector overhauls. While officials champion the country’s newfound autonomy, the agreement underscores a paradox: true economic sovereignty cannot be declared in speeches alone. It must be built on the ability to self-finance development without external constraints.
For Niger, this deal serves as a turning point—one that highlights the tension between national ambition and the practical realities of fiscal survival. The question now is whether the refoundation agenda can thrive under the IMF’s watchful eye, or if the country’s economic destiny remains hostage to the institutions it seeks to escape.
The fine print: what the IMF’s conditions mean for Niger
- Fiscal restructuring: Expanding tax bases and improving revenue collection to reduce reliance on external borrowing.
- Debt discipline: Implementing strict limits on public borrowing to prevent unsustainable accumulation.
- Financial transparency: Strengthening governance in the banking sector to curb corruption and mismanagement.
- Monetary stability: Adopting policies to stabilize inflation and ensure price predictability for households.
A moment of reckoning for Niger’s economic future
The IMF deal is more than just a financial lifeline—it’s a litmus test for Niger’s refoundation vision. As the government balances between domestic priorities and foreign oversight, one truth emerges: economic independence is not a slogan but a daily struggle. Whether this program marks the beginning of a new era or simply another chapter in external dependency may well define Niger’s path forward.